Affiliate Program Management: A Merchant’s Setup and Operations Guide
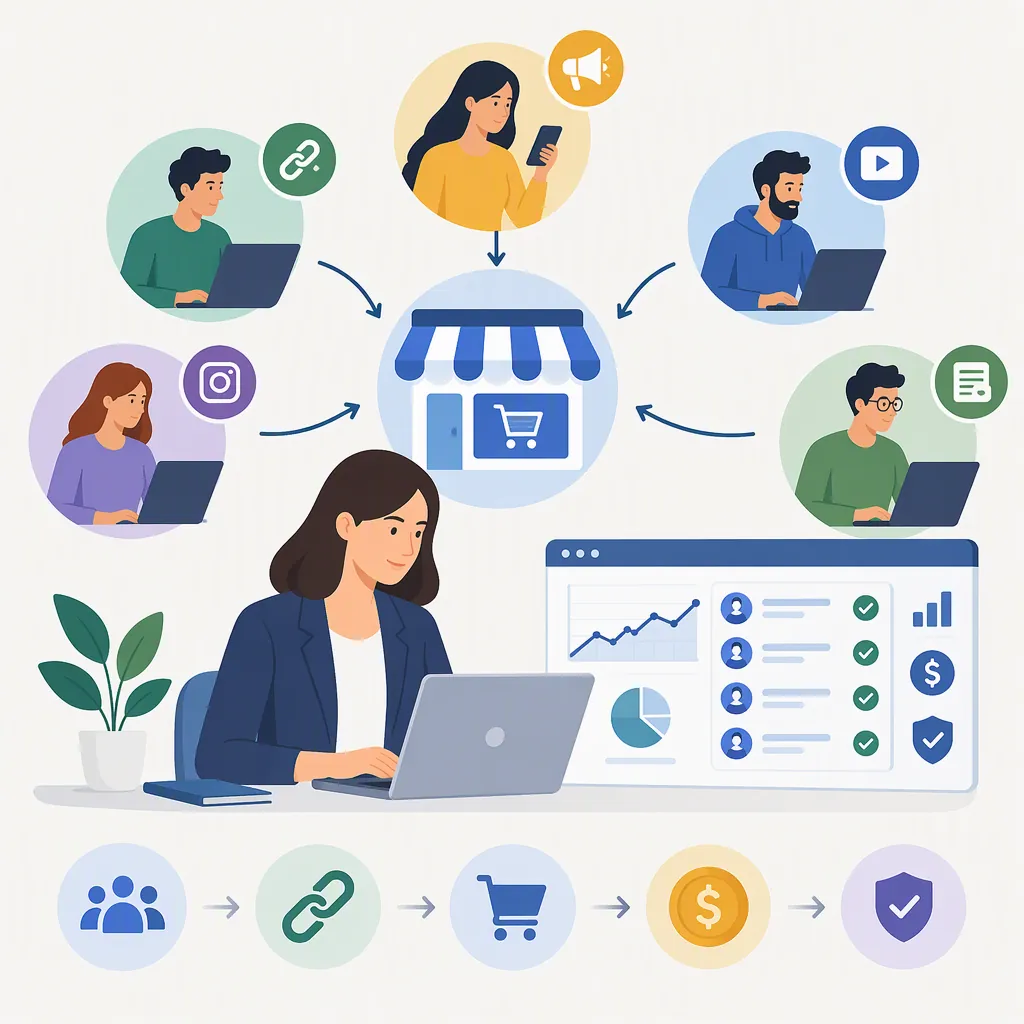
Affiliate program management is the ongoing work of recruiting and onboarding partners, defining commissions, tracking referrals, reviewing compliance, supporting affiliates, and improving program performance. For merchants, a practical starting point is to document the qualifying conversion and payment rules, test tracking, assign an accountable manager, and establish a recurring review process. Software supports these tasks but does not replace program ownership. [c1] [c2]
Define the Program Before Choosing Tools
A merchant affiliate program pays third-party partners for agreed outcomes, such as sales or qualified leads. Managing it involves more than distributing referral links: recruitment, activation, communication, compliance, and optimization are recurring responsibilities. [c1]
Start with a written operating brief. Decide which products, audiences, markets, and promotional methods belong in the program. Then define what counts as a payable conversion and who can approve exceptions.
Keep the commercial objective specific. For example, a merchant might prioritize eligible new-customer purchases rather than all attributed orders. That is a proposed program design, not a universal requirement.
Assign responsibility across the workflow: a program manager for partner support, a technical owner for tracking, and a finance owner for payment reconciliation. One person may hold multiple roles, but each responsibility should be explicit.
Program Operating Brief
- Business objective: [Describe the outcome the program should support.]
- Eligible products and markets: [List inclusions and exclusions.]
- Qualifying conversion: [Define the payable event and validation criteria.]
- Eligible affiliates: [Describe audience fit and permitted promotional methods.]
- Commission and attribution rules: [Record the agreed calculation and crediting rules.]
- Program owner: [Assign responsibility for operations and exceptions.]
- Technical owner: [Assign responsibility for tracking and incident response.]
- Finance owner: [Assign responsibility for approval, reconciliation, and payment.]
- Review schedule: [Set a cadence that fits transaction volume and risk.]
Choose Compensation and Write Clear Terms
The supplied management reference describes pay-per-sale, pay-per-lead, pay-per-click, and pay-per-call compensation models. It also cautions that click-based compensation needs strong fraud controls and that lead quality requires attention. [c1]
Choose a model around the outcome you can validate, not simply the easiest event to count.
| Model | Decision to Resolve Before Launch |
|---|---|
| Pay per sale | Which order value is commissionable, and how are refunds treated? |
| Pay per lead | What makes a lead qualified, unique, and eligible? |
| Pay per click | How will invalid or manipulated clicks be identified? |
| Pay per call | What call criteria and tracking records establish eligibility? |
Set commission amounts using your own economics. Account for discounts, fulfillment or service costs, expected returns, payment fees, and program operating costs. The supplied references do not establish an appropriate rate for every merchant.
Document the calculation base, attribution window, competing-referral rules, validation period, payout schedule, thresholds, and reversal reasons. Include policies for paid search, trademark use, coupons, self-referrals, and any partner intermediaries. Program agreements and transaction reviews are both part of the management practices described in the reference. [c1]
Treat this as an operating checklist, not a ready-to-use legal agreement. Obtain appropriate review of advertising, privacy, tax, and contractual requirements for the markets involved.
Evaluate Tracking and Workflow Coverage
Affiliate management software commonly supports referral tracking, commission calculations, onboarding workflows, reporting, and payouts. The supplied software overview distinguishes e-commerce, subscription, and multi-channel use cases. [c3]
Use those categories as evaluation prompts, not as proof that a particular platform fits your implementation. Public feature descriptions do not verify performance in your checkout, billing system, or consent configuration.
A proposed evaluation checklist is:
- Conversion coverage: Can the workflow record the events your terms make payable?
- Attribution rules: Can it implement the agreed window and resolve link-versus-coupon conflicts?
- Commission adjustments: Can you reconcile refunds, cancellations, and duplicate records?
- Partner access: Can affiliates find current links, assets, and understandable earnings records?
- Operational controls: Are permissions, approval steps, exports, and adjustment histories adequate?
- Integration ownership: Who investigates missing events or synchronization failures?
A CRM may organize applications, communication, and follow-ups, while an affiliate-specific system handles conversion attribution and commissions. The references discuss CRM-based workflows and integrations, but do not establish that a CRM alone covers every merchant’s tracking requirements. [c2] [c3]
Before launch, test the complete path from referral to payment record. After changes to checkout, domains, or landing pages, repeat the relevant tests. The management reference identifies website changes as a possible source of tracking downtime. [c1]
Referral Tracking Acceptance Test
For each test, record the expected result, observed result, evidence, owner, and resolution status.

- Referral link → eligible conversion → expected affiliate credit.
- No affiliate referral → conversion → no unintended affiliate credit.
- Two affiliate referrals → conversion → published attribution rule applied.
- Referral link plus coupon → conversion → published conflict rule applied.
- Duplicate conversion event → no duplicate commission.
- Refund or cancellation → adjustment matches program terms.
- Referral outside the attribution window → eligibility matches program terms.
- Website redirect or checkout change → referral information remains intact where expected.
- Approved commission → payout record → finance reconciliation.

Launch decision: [Record unresolved issues and the person approving release.]
Recruit for Fit and Support Activation
The references emphasize reviewing prospective partners and providing structured onboarding with product information, creative assets, and commission rules. They also distinguish recruiting affiliates from activating those who have already joined. [c1] [c2]
For application review, consider audience relevance, actual promotional properties, proposed traffic sources, target markets, and willingness to follow program terms. Treat audience size as one input rather than the whole decision.
An onboarding pack should make the next steps clear: how to access links, what claims are supported, which methods are permitted, where current assets live, and how commissions become payable. Explain how to report a tracking problem and who handles questions.
Segment support by activity:
- Approved but inactive: Ask whether links, setup, or product information are blocking participation.
- Sending traffic without eligible conversions: Review tracking, audience fit, messaging, and landing pages before drawing conclusions.
- Producing eligible conversions: Review quality and economics, then discuss relevant opportunities.
This activity-based approach follows the management reference’s distinction between stagnant, traffic-driving, and sales- or lead-producing affiliates. [c1] Do not interpret inactivity as misconduct or promise earnings as an activation tactic.
Establish a Review and Payment Routine
Transaction review can reveal incorrect rates, agreement inconsistencies, suspicious patterns, and opportunities to support partners. The management reference explicitly notes that a conversion spike is a reason to investigate, not proof of fraud. [c1]
A proposed starting routine is to review urgent tracking and payment issues frequently, applications and partner support weekly, and program economics monthly. Adjust the cadence to your volume and risk rather than treating these intervals as industry standards.
Separate detection from decisions. Preserve relevant records, compare activity with the agreed terms, investigate explanations, and document the reason for any adjustment. Avoid automatically withholding commissions solely because an alert fired.
Before a payout run, reconcile eligible conversions, reversals, approved commissions, and payment status. Explain disputed or reversed items through the program’s established process.
For tracking incidents, record the affected period, known limitations, remediation, and partner communication. The supplied management reference recommends acknowledging tracking outages and taking corrective action. Any compensation method should be documented and supported by the available evidence, not presented as an exact reconstruction when records are incomplete. [c1]
Recurring Operations Review
- Review tracking failures and unresolved partner questions.
- Process applications against documented eligibility criteria.
- Check commission rates and adjustments against agreed terms.
- Investigate unusual traffic, conversion, and reversal patterns.
- Confirm that links, offers, and creative assets are current.
- Reconcile approved commissions with payment records.
- Record each issue: [Evidence], [Owner], [Decision], [Due date].
- Communicate material changes and resolved incidents to affected partners.
- Close the review with: [Completed items], [Open risks], [Next review date].
Measure Validated Outcomes, Not Just Activity
The references identify clicks, conversions, conversion rate, revenue, average order value, partner retention, and new-versus-returning customer information as useful reporting inputs. [c2] [c3]
Define each metric before comparing affiliates. In particular, distinguish recorded conversions from validated payable conversions and attributed revenue from revenue after refunds.
A compact report can include:
- Eligible conversions and net attributed revenue.
- Click-to-eligible-conversion rate, with the denominator stated.
- Commissions approved, reversed, paid, and outstanding.
- Refund or rejection rate, with reasons.
- Active partners, with “active” explicitly defined.
- New-versus-returning customer mix, where reliably available.
- Tracking incidents and unresolved attribution disputes.
For an internal contribution estimate, subtract relevant product or service costs, commissions, and allocated program costs from the revenue basis you select. State exclusions so readers do not confuse the estimate with full business profit.
Attribution records which partner receives credit under your rules; it does not, by itself, establish whether the purchase would have happened without that referral. Treat claims of incremental growth as a separate evaluation question. Use reporting to identify questions and test changes, not to assume that every attributed sale is newly created demand.
Compare In-House, Outsourced, and Hybrid Management
The management references describe in-house, outsourced, and combined approaches. An outsourced program management agency may handle strategy, recruitment, partner communication, reporting, and compliance monitoring; its scope varies with program needs. [c1] [c4]
| Approach | Main Decision to Resolve |
|---|---|
| In-house | Does the team have time and expertise for both relationships and daily operations? |
| Outsourced | Are deliverables, fees, authority, access, and accountability clearly defined? |
| Hybrid | Is the division of responsibilities explicit enough to prevent gaps or duplicate work? |
Compare total operating cost and coverage rather than assuming one model is cheaper. Include internal time, software, agency fees, integration support, and finance work.
Keep merchant approval rights clear for commercial terms, policy changes, and material payment disputes. For any external engagement, define data access, account ownership, reporting expectations, and handover requirements.
Evidence limits: This guide uses the supplied public management articles and vendor-published overviews. They support the workflow concepts discussed here, but are not independent audits, legal guidance, or evidence of a particular merchant’s results. No software ranking, commission benchmark, or revenue forecast is established by this article.
FAQ
Is Affiliate Program Management the Same as Affiliate Software?
No. Management includes commercial decisions, partner relationships, compliance review, and optimization. Software supports tasks such as tracking, calculations, communication, and reporting. A merchant still needs an accountable owner for the program and its exceptions. [c1] [c3]
What Commission Rate Should a Merchant Offer?
There is no universal rate established by the supplied sources. Choose a commission model and amount that fit the qualifying event and your economics. Define the calculation base, eligibility, refund treatment, and payment timing before comparing offers. The management reference describes several compensation models rather than one formula for all merchants. [c1]
Can a CRM Run an Affiliate Program?
A CRM can support application management, communication, and follow-ups. Whether it covers attribution, commission adjustments, and payouts depends on the implementation and connected systems. The supplied CRM and software articles discuss these workflows, but do not verify complete coverage for every merchant. [c2] [c3]
When Should a Merchant Consider Outsourced Management?
Consider it when the team lacks the capacity or expertise to cover strategy, recruitment, partner support, and recurring operations. Compare the proposed scope, fees, reporting, access controls, and handover terms with the work your team can perform internally. Agency support is an operating option, not a guarantee of growth. [c4]