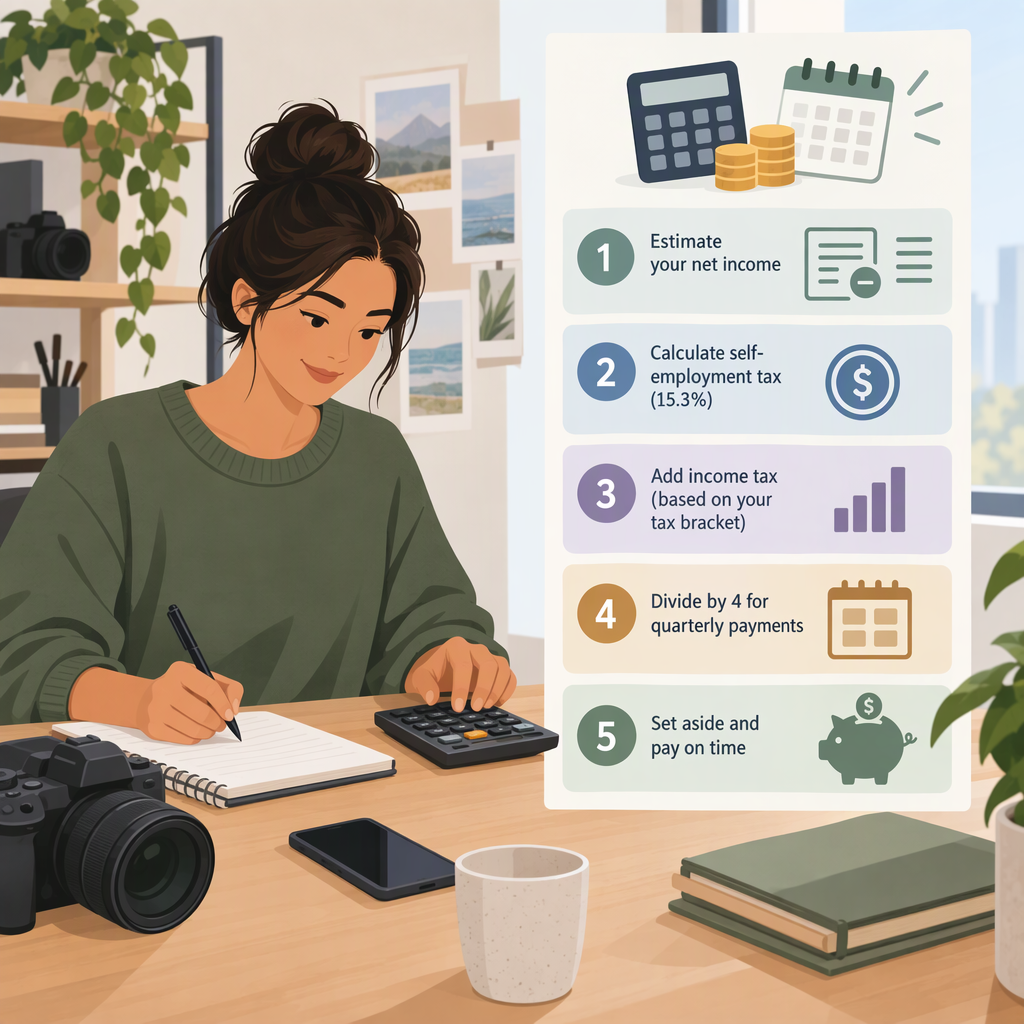
How to Calculate Estimated Taxes for Self-Employed Creators (2026)
If you’re self-employed, estimate your 2026 federal income tax and self-employment tax together, then use the IRS’s 2026 Form 1040-ES to work out how much to pay after withholding, refundable credits, and any estimated payments you’ve already made. Start with projected business profit, not gross receipts: profit generally means business income minus allowable business expenses. Form 1040-ES is the IRS worksheet for estimating the tax and determining payments; Schedule SE calculates self-employment tax. (irs.gov)
This guide covers U.S. federal individual estimated taxes for tax year 2026. It’s an estimate, not a guarantee of your final tax bill. State and local estimates are separate.
How to Calculate Your Estimated Taxes
- Project your full-year income. Estimate your business income and allowable expenses through December 31, then calculate projected net profit. Add other expected income that may affect your federal tax, such as wages, interest, dividends, or capital gains. Update your projection as the year changes.
- Gather deductions, credits, withholding, and payments. Use the current-year Form 1040-ES worksheet and your prior-year return. Include only deductions and credits you reasonably expect to qualify for. Record federal income tax withholding from jobs or other sources, refundable credits, and estimated payments already made.
- Estimate federal income tax. Apply the 2026 worksheet’s instructions to your expected income and applicable deductions, then estimate income tax using the filing status and tax-year rules that apply to you. The amount depends on your full tax situation—not business profit alone.
- Estimate self-employment tax separately. Use Schedule SE. For many self-employed people, net earnings subject to this tax are generally 92.35% of net profit. The standard self-employment tax rate is 15.3%—12.4% Social Security plus 2.9% Medicare—but the Social Security portion is subject to a wage-base limit, and other rules can affect the result. The IRS says the 2026 Social Security wage base is $184,500, counting applicable wages and self-employment earnings together. (irs.gov)
- Combine the estimated taxes and subtract amounts already paid. Form 1040-ES estimates income tax and self-employment tax, along with other applicable taxes. Apply expected withholding, refundable credits, and estimated payments as the worksheet directs. Its result helps determine whether you may need to pay more during the year and how much.
- Recalculate when your forecast changes. A new client, a large expense, or a slow season can change projected profit and the amount to pay. Use the current-year worksheet again rather than assuming an earlier estimate still fits.
A Limited Example: Estimating the Self-Employment Tax Component
Suppose a sole proprietor projects $60,000 of 2026 net profit, has no wages subject to Social Security tax, and all the profit is subject to the ordinary Schedule SE calculation. For illustration, 92.35% of $60,000 is $55,410; multiplying that by 15.3% gives about $8,478 in estimated self-employment tax before considering any special circumstances. This is only the self-employment tax component—it does not calculate income tax or the person’s total estimated payment. Actual Schedule SE results depend on the taxpayer’s facts and the applicable instructions. (irs.gov)
Do You Need to Make Estimated Payments?
For 2026, the general IRS rule says you generally need to make estimated tax payments if both conditions apply:
- After subtracting withholding and refundable credits, you expect to owe at least $1,000 for the year; and
- You expect withholding and refundable credits to be less than the smaller of 90% of your 2026 tax or 100% of your 2025 tax. The 2025 return must cover 12 months.
For certain higher-income taxpayers, the prior-year comparison is generally 110% rather than 100% if 2025 adjusted gross income was more than $150,000, or $75,000 if married filing separately. Special rules also apply to some farmers and fishers and other situations. Check the 2026 Form 1040-ES instructions for the rules and exceptions that apply to you. (irs.gov)
These comparisons can help assess underpayment-penalty risk. They do not establish that your final tax will equal the amount you paid. You may still owe more when you file. Conversely, a penalty may be possible for late or insufficient payments even if you later expect a refund. (irs.gov)
How Much to Pay and When In 2026
Follow the installment amount calculated under Form 1040-ES; don’t automatically divide your total projected tax bill by four. The usual federal payment periods cover unequal parts of the calendar year:
| 2026 income period | Federal estimated-tax due date |
|---|---|
| January 1–March 31 | April 15, 2026 |
| April 1–May 31 | June 15, 2026 |
| June 1–August 31 | September 15, 2026 |
| September 1–December 31 | January 15, 2027 |
As of November 13, 2026, the first three dates have passed; January 15, 2027 is the next ordinary due date. If you missed an earlier payment, don’t assume a later payment erases any penalty for an earlier period. Check the IRS instructions or penalty guidance for your circumstances. If a due date falls on a weekend or legal holiday, the IRS says payment is timely when made on the next business day. (irs.gov)
Simple installment arithmetic: If the applicable Form 1040-ES calculation says you need to pay $12,000 through estimated payments and your facts call for four equal installments, $12,000 ÷ 4 = $3,000 per installment. This illustrates the division only; use the official worksheet to determine the required annual amount and installments.
If Your Income Is Uneven
If a creator earns substantially more in one part of the year—for example, from a seasonal launch or a large project—the four equal-payment assumption may not reflect when income arrived. The IRS says taxpayers with uneven income may be able to reduce or avoid a penalty by annualizing income and making unequal payments. This requires the applicable annualized-income worksheet and, where needed, Form 2210 Schedule AI; it is not simply a matter of paying less in a slow quarter. (irs.gov)
Does a Federal Estimate Include State or Local Taxes?
No. The federal Form 1040-ES calculation does not determine whether you must make state or local estimated-tax payments. Requirements and deadlines depend on the jurisdiction. Check the official tax authority for the state or locality where you have filing obligations.
Irs Forms and Records to Use
- 2026 Form 1040-ES: Start here for the estimated-tax worksheet, payment calculation, and federal instructions. Use the current version; the IRS has published corrections to the 2026 form, including to state and local income tax deduction information and payment mailing addresses. (irs.gov)
- Schedule SE and its 2026 instructions: Use these to calculate self-employment tax and the related deduction for the income-tax calculation. (irs.gov)
- Your 2025 federal return: The 2026 payment worksheet uses prior-year information for its comparison, so have the return available. (irs.gov)
- Current-year income and payment records: Keep a running projection of business income and allowable expenses, other income, withholding, credits, and estimated payments already made. These figures help you update the estimate.
For complex circumstances—such as multiple income sources, substantial wage income, prior-year exceptions, or irregular business earnings—the current IRS instructions or individualized tax advice can help determine which calculation applies.